Saudi Arabia has found itself at the centre of the fallout from the US-Iran conflict. The world’s largest oil exporter is grappling with severe disruptions to its oil sector, with crude production falling to its lowest level in more than three decades.
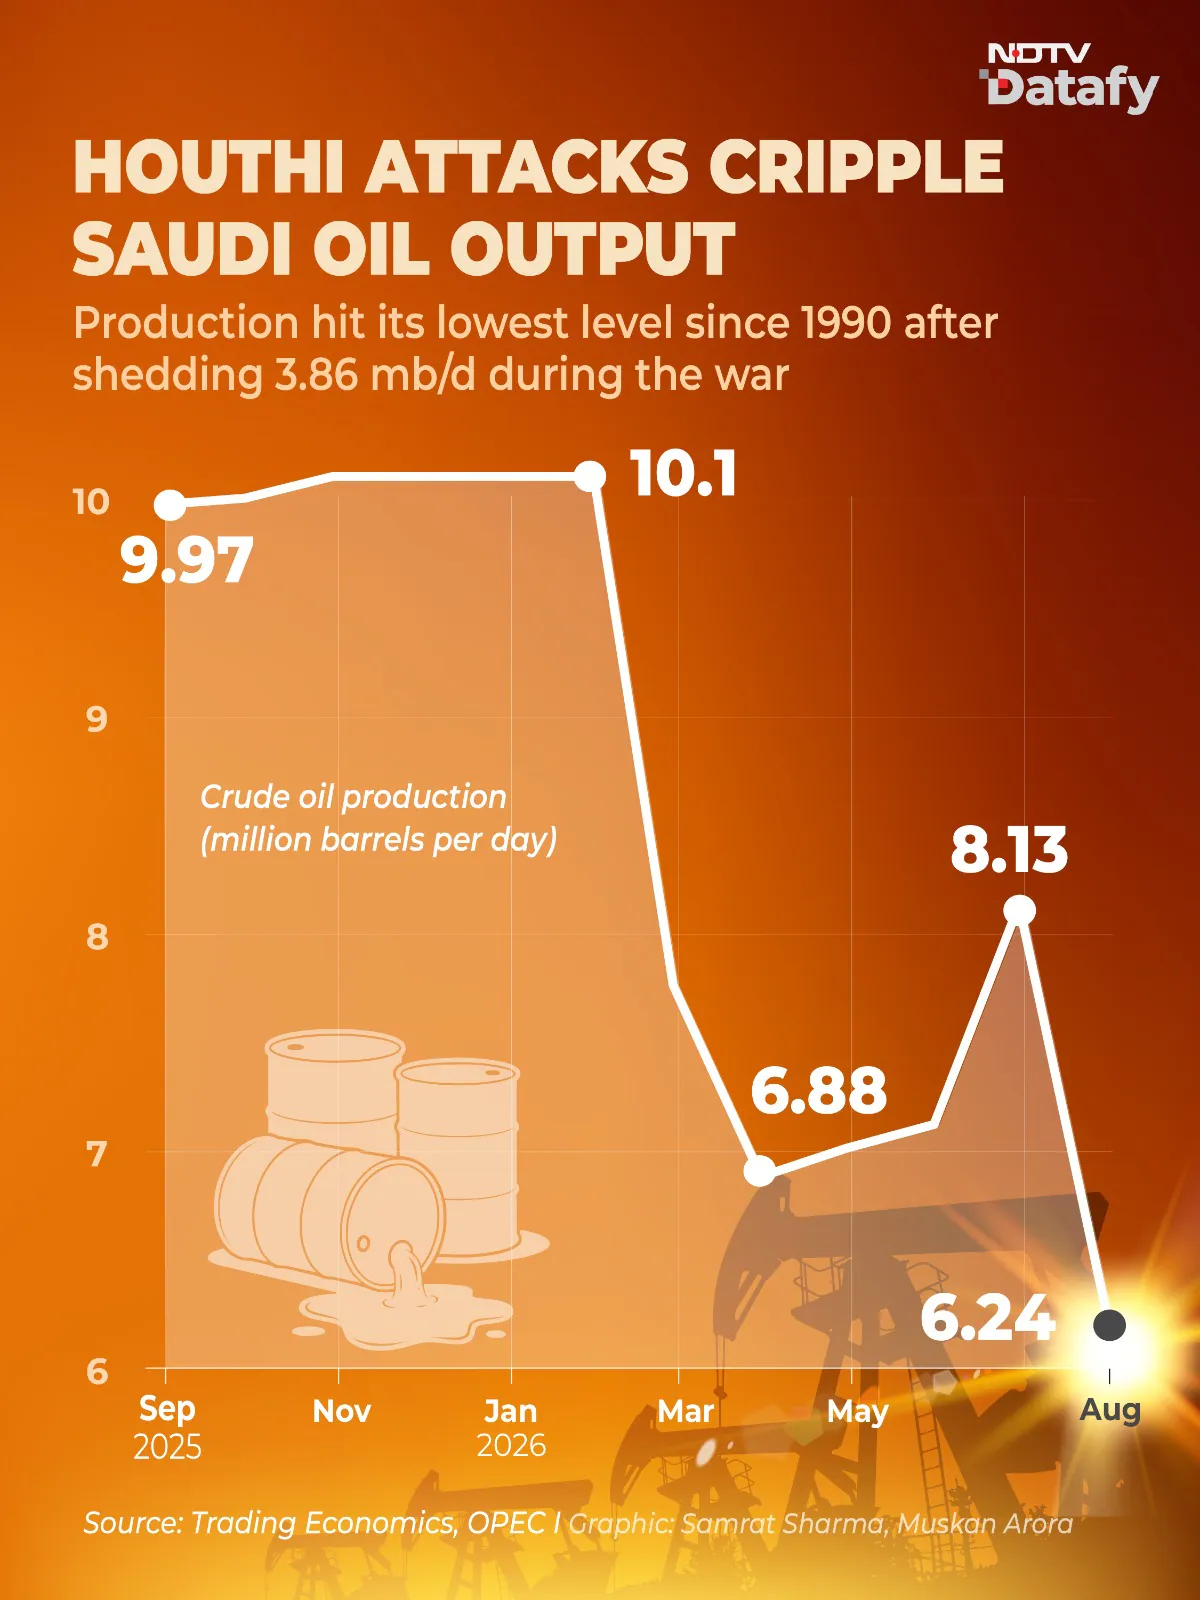
Saudi Arabia’s crude oil production dropped by 3.86 million barrels per day (mb/d) from pre-war levels after the conflict began in February 2026. Output, which held steady at around 10.1 mb/d between November 2025 and February 2026, fell to 7.76 mb/d in March and declined further to 6.24 mb/d in August, the lowest level since 1990.
The decline comes amid a series of attacks on Saudi energy infrastructure. The Saudi Press Agency (SPA) recently reported that the Houthi militia continues to target the kingdom’s critical infrastructure and national assets. In a separate statement, the Saudi Ministry of Energy said the East-West Pipeline, which carries crude from eastern Saudi Arabia to the Red Sea, was attacked on September 10.
“An official source at the Ministry of Energy stated that the East-West Pipeline in the Riyadh and Madinah regions was subjected to multiple attacks on the morning of Thursday, September 10, 2026. The pipeline was shut down as a precautionary measure,” SPA reported.
The disruption has raised concerns about global oil supplies. Recent reports suggest that Saudi Aramco has halted supplies to some Indian refiners and reduced allocations to several European customers, highlighting the strain on the kingdom’s export capacity. Yet while Gulf producers struggle with supply disruptions, oil producers outside the region have moved quickly to fill part of the gap.
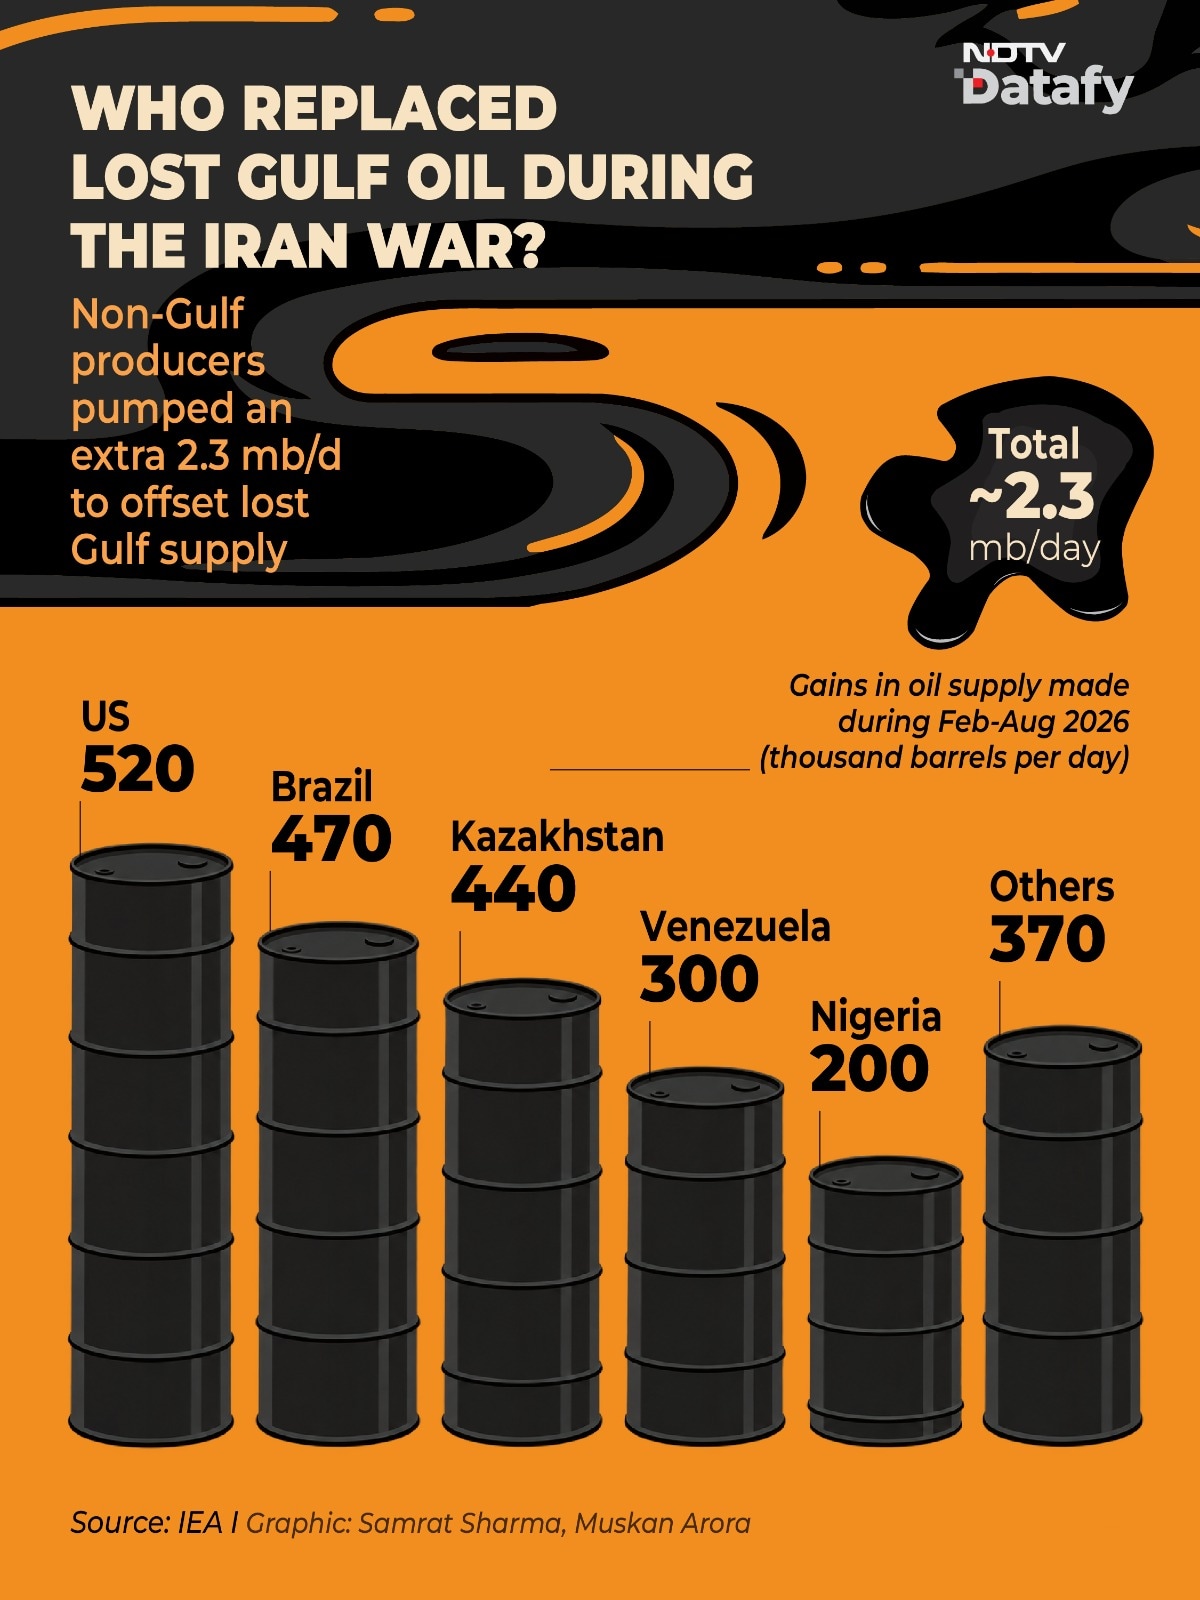
According to the International Energy Agency (IEA), non-Gulf producers have increased output by 2.3 mb/d since the conflict began in February. The largest increase came from the United States, which boosted production by 520 kb/d, followed by Brazil (+470 kb/d), Kazakhstan (+440 kb/d), Venezuela (+300 kb/d) and Nigeria (+200 kb/d). Together, these five countries added nearly 1.93 mb/d of supply to global markets.
Six months into the conflict, oil production and exports from the Gulf remain heavily constrained. Oil flows through the Strait of Hormuz averaged just 7.6 mb/d in August, about 13.1 mb/d below pre-war levels. However, the actual supply shortfall has been smaller than the headline export losses suggest.
IEA balances indicate a deficit of 2.2 mb/d in the second quarter of 2026 and 1.7 mb/d in the third quarter, thanks to a combination of alternative export routes, higher production outside the Gulf and inventory drawdowns. As shipping through the Strait of Hormuz became increasingly difficult, Saudi Arabia and the United Arab Emirates redirected as much crude as possible through routes that bypass the chokepoint. As Gulf production remains under pressure, the burden of balancing global oil markets is increasingly falling on producers far beyond the Middle East.