Quick overview
- Palantir Technologies Inc. is trading near $185, close to its 52-week high of $207.52, driven by strong AI demand and new partnerships.
- CEO Alex Karp’s recent comments on federal AI regulations emphasize the company’s focus on sovereign AI infrastructure and enterprise data control.
- The company’s Q2 revenue surged 93% year over year to approximately $1.9 billion, with record U.S. commercial bookings of $2.1 billion.
- Analysts have mixed views on Palantir’s valuation, with price targets ranging from $80 to $255, while the stock’s high trailing P/E ratio raises concerns.
Palantir Technologies Inc. (NASDAQ: PLTR) is trading near $185, before yesterday’s close of $183.09 and close to its 52-week high of $207.52. The AI software company is continuing to digest fresh executive commentary, new analyst targets, and the ongoing debate around its valuation.
Karp’s Push for Federal AI Guardrails Supports the Sovereign AI Story
In recent days, some of the gains have been linked to comments by CEO Alex Karp regarding the rules and liabilities that need to be in place for broader enterprise AI use. His comments highlighted Palantir’s emphasis on sovereign AI infrastructure, enterprise data control, and the security considerations of implementing AI.
The comments also came as Palantir announced new partnerships with Nvidia, Nebius, and Method Security. Such partnerships enhance the company’s ties to the broader ecosystem surrounding AI infrastructure, providing investors with greater visibility into more than just the company’s core government activities.
Record Commercial Bookings Keep Growth on Track
The bulls are still holding onto the fundamentals of Palantir. The company’s Q2 revenue increased 93% year over year to approximately $1.9 billion, and the company now forecasts total 2026 revenue to be approximately $8.15 billion. That outlook is being bolstered by record U.S. commercial bookings worth of $2.1 billion.
Adjusted EPS was also $0.41, off by nearly 19% from the $0.34 consensus. The company’s EBITDA margin has also risen above 32%, which highlights the pace of improvement in profitability as a result of the revenue growth. Palantir will release its next earnings on November 9.
Analysts Split Between Higher Targets and Valuation Concerns
UBS has increased its price target to $250 from $220 this month, and Wedbush analyst Dan Ives stated that Palantir may be valued at a trillion dollars someday if its AI platform keeps gaining traction.
Analysts currently have an average price target on the stock of approximately $196.84, while 21 analysts rate the stock as a Buy and only 2 analysts are assigning a Sell rating. However, estimates range from as high as $255 to as low as $80, showing the wide gap in expectations around Palantir’s valuation. Valuation is definitely an issue as the stock has a trailing P/E over 150.
Cathie Wood’s ARK has also recently cut back on its stake in Palantir, despite ongoing purchases of other AI stocks. That suggests some investors are taking profits after the stock’s strong run, despite the broader interest in AI.
Analyst Targets and What to Watch Next
On the technical side, Palantir is still holding within its 52-week span and above its 200-day moving average, maintaining the longer term trend positive. The MACD (12,26,9) indicator is -1.168, which is neutral, and the 14 period RSI is also in neutral to firm zone around 61.00. The Williams %R reading around -15.8 is signaling overbought conditions, though, which means the stock may be taking a pause following its recent run.
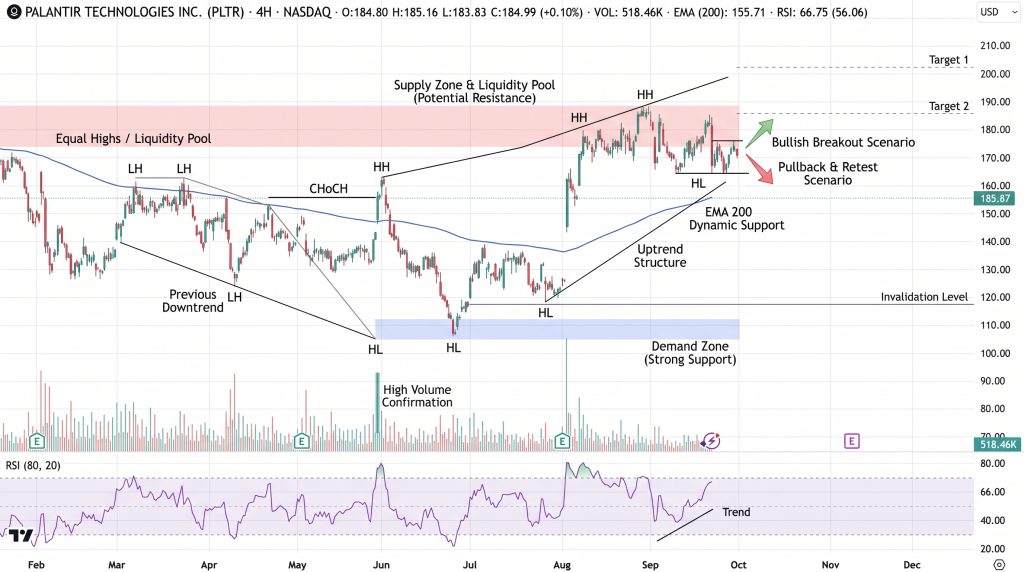
Short-term resistance is found at the 52-week high around $207.52. If it keeps pushing above that level, the $220-250 range may become significant, which is around the level UBS has set as a price target. On the negative side, support is near $182, close to today’s intraday low, while the higher support area is around $167, where the market found buyers during the last pullback from the September high of $188.
The company has several weeks left before it releases its next earnings report, so its near-term path may be heavily influenced by announcements of new AI partnerships, CEO remarks, and the ongoing debate over the sustainability of Palantir’s fast government and commercial bookings growth. Breaking above $182 would maintain the current price structure, whereas a break under $167 would be a bigger pullback.
FAQs
- Why is Palantir stock rising?
Palantir has benefited from strong AI demand, rapid revenue growth, record U.S. commercial bookings, and new partnerships across the AI infrastructure sector.
- What are the key support and resistance levels for PLTR stock?
The main resistance level is around $207.52, the current 52-week high. Support is near $182, followed by a stronger zone around $167.
Bottom Line:
Palantir continues to benefit from strong AI adoption, commercial bookings, and expanding profitability, but its high valuation remains a key consideration. The next major catalysts are AI partnerships, executive commentary, and the November 9 earnings report.

Arslan Ali Butt
Lead Markets Analyst – Multi-Asset (FX, Commodities, Crypto)
Arslan Ali Butt serves as the Lead Commodities and Indices Analyst, bringing a wealth of expertise to the field. With an MBA in Behavioral Finance and active progress towards a Ph.D., Arslan possesses a deep understanding of market dynamics.
His professional journey includes a significant role as a senior analyst at a leading brokerage firm, complementing his extensive experience as a market analyst and day trader. Adept in educating others, Arslan has a commendable track record as an instructor and public speaker.
His incisive analyses, particularly within the realms of cryptocurrency and forex markets, are showcased across esteemed financial publications such as ForexCrunch, InsideBitcoins, and EconomyWatch, solidifying his reputation in the financial community.